Help To Buy Scheme
Tax

Help To Buy Scheme

Nick Charalambous
Nick Charalambous5th Aug 2020 • 2 min read

The Help to Buy incentive, also known as the Help to Buy scheme, is a Government tax refund scheme designed to help first-time buyers get the deposit needed to buy a newly built home. Borrowers can claim a maximum of 10% of the value of the property or €30,000 – whichever is lower.

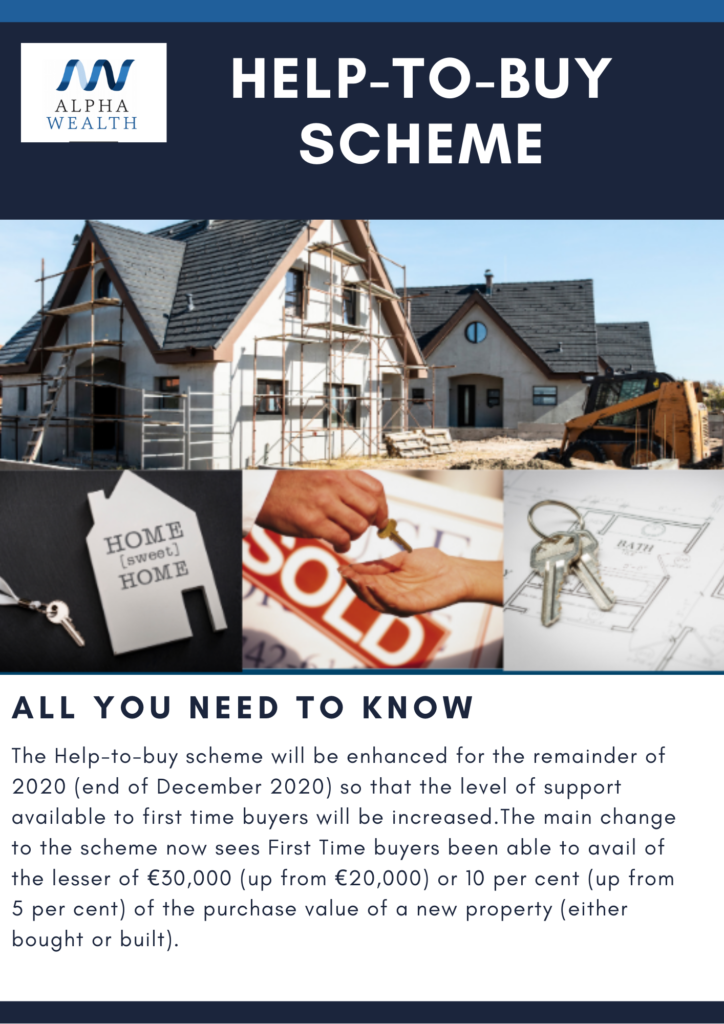
The Help-To-Buy scheme will be enhanced for the remainder of 2020 and up until the end of December 2020, so that the level of support available to first-time buyers will be increased. The main change to the scheme now sees First Time Buyers being able to avail of the lesser of €30,000, up from €20,000, or 10%, up from 5%, of the purchase value of a new property, either brought or built.

Information on the help to buy scheme and how it helps approved developers and contractors
Purchase Value and Mortgage information on the help to buy scheme in Ireland

The purchase value of a new build means the price that you bought it for. For Self-Build Properties, the purchase value is the approved valuation by the lender at the time that you took out the mortgage. If the property is bought between the 19th of July 2016 and the 31st of December 2016, the purchase price must be €600,000 or less. If bought after January 1st 2017, it must be €500,000 or less.

How much you can claim on the help to buy scheme in Ireland
How to apply for the help to buy scheme using the ROS

How to apply for the Help To Buy

Applicants must use myAccount or Revenue’s Online Services (ROS) to apply for the Help To Buy scheme online. For help with this or for more information, contact our team of financial advisors today at 021 2061780 or via email at contact@alphawealth.ie

Nick Charalambous

Nick Charalambous

5th Aug 2020

Share this post

LinkedInTwitterFacebook

Related articles

Front of Irish Government Building
Tax

What Is the Government’s New Savings and Investment Scheme?

The Government is developing a new Savings and Investment Scheme which is expected to become available in 2027. The new savings and investment scheme is designed to make investing more accessible and tax-efficient for Irish savers. It will allow individuals to invest up to a set annual limit through an investment account, with no minimum contribution required.

Why does the Government want people to invest? 

Keeping money in a deposit account can be a suitable option for many people, particularly when saving for short-term needs or keeping an emergency fund, the Government argues that too much household wealth remains in low deposits. 

The concern is that money held in cash may not grow significantly over time, particularly when inflation reduces its buying power. 

The Government therefore wants to give people another option, which is investing some of their longer-term savings in an investment account. 

The aim is not simply to get people to take more risk. Alternatively, the Government wants to make investing more accessible to people who may traditionally have kept all their savings in cash.  

Who is the scheme for? 

  • Designed for Irish tax residents aged 18 and over who hold a Personal Public Service Number (PPSN). 
  • Aimed at everyday savers and middle-income households. 
  • Encourages people to move some of their savings from bank accounts earning low levels of interest into capital-market investments. 
  • Designed to make investing more straightforward and accessible, rather than being aimed solely at experienced investors. 
  • There will be no minimum contribution, allowing people to start with an amount they are comfortable investing. 
  • An annual investment limit will apply. 
  • Provides people another option for money they can afford to invest for the long term, while keeping cash savings available for short-term needs and emergencies. 

 What are the tax benefits? 

The exact tax-free threshold, flat tax rate and annual contribution limit have not yet been announced and are expected to form part of Budget 2027 announcing on October 6th. 

Some thoughts: 

  1. 76% of people support the introduction of the Government’s savings and investment scheme. 
  2. 1 in 5 are concerned that the scheme will mainly benefit wealthier households.
  3. 1 in 3 are worried about potentially losing money through the scheme.
  4. 19% lack trust in the Government’s ability to oversee and manage the scheme.
  5. 19% are concerned about potential fees and tax implications. 

This is a positive way forward for Irish savers, making investing more accessible and helping more people consider the potential of long-term investing. Stay tuned for further updates as we get closer to Budget 2027. 


READ MORE 17th Sept 2026
Personal Tax Tips in Ireland
Tax

Personal Tax Tips in Ireland

Income protection policy

Tax relief is applicable when you effect an income protection policy (policy taken out in case of an accident, illness etc). The tax relief is available at your marginal rate of tax of 20%/40%.

Health insurance

We recommend if you  are a contractor/ permanent employee & pay your health insurance yourself, you can benefit from tax relief at a rate of 20%  on the cost of the premium – reducing your net cost.

Maternity Leave

If you are a women who is returning to work from maternity leave may also be able to benefit from unused tax credits. You should ensure your  payroll company or employer confirms all your tax credits are being utilised.

DIRT

If you are a first-time buyer you can claim DIRT on the money you save for a deposit for your home. This also applies to first time buyers who self-build a home to live in.

Tax-saver commuter tickets

Do you use public transport to get to work on a daily basis? Ask your payroll provider or employer to purchase the commuter tickets on your behalf in order to claim tax relief.
Depending on the mode of transport and your rate of pay you can save approximately anything between a third and half of the costs.

Flat rate expenses

Professionals such as teachers, nurses, doctors and tradesmen can claim back an annual expense allowance to cover required items like tools, uniforms etc. that are not covered by your employer.

Civil partnership / Marriage

Are you married or have you entered into a civil partnership in the last few years and didn’t inform Revenue? If one of you is not working and you become jointly assessed it will increase your take home pay by a few thousand (on the average industrial wage).
Once you are married or in a civil partnership, you can share tax credits and have more of your income taxed at the lower rate, which can boost your take-home pay if you fi le as jointly assessed.

Pension contributions

PAYE employees  can pay into a personal pension scheme and reduce your tax burden as a result. Use Alpha Wealth to advise on the most appropriate scheme which meets your needs.
A great quote from Benjamin Franklin is  “In this world nothing can be said to be certain except death and taxes”. If you are sturgling to sort our your personal taxes why don’t you book a free consultation today.

TAXES ARE TAXES

TAXES ARE TAXES
READ MORE 21st Apr 2017