What Ireland’s New Personal Investment Account Means for You
Advice

What Ireland’s New Personal Investment Account Means for You

Nick Charalambous
Nick Charalambous14th Oct 2026 • 6 min read

Budget 2027 introduced a significant development for investors in Ireland: the new Personal Investment Account (PIA). Designed to simplify investing and encourage more people to grow their money, the scheme could offer a new way to invest for the future. 

With a planned launch date of 1 July 2027, what do we know so far, how will the PIA work, and what could it mean for you? 

At Alpha Wealth, we’re following the latest developments closely. Here’s what you need to know. 

What is the Personal Investment Account? 

The Personal Investment Account is a new investment framework announced in Budget 2027. It aims to make investing more accessible by introducing a simpler tax structure for eligible investments. 

Under the announced framework, the first €50,000 of your account’s value will fall below the threshold for the annual Personal Investment Account tax. A 1% annual tax will apply to the value above that amount. 

What are the key features of the PIA? 

The Government has announced several important features: 

  • €50,000 tax-free threshold: The first €50,000 of your account’s value will fall below the annual tax threshold. 
  • 1% annual tax above the threshold: The tax applies to the account value exceeding €50,000, rather than solely to investment profits. 
  • No deemed disposal: The deemed disposal rule will not apply to eligible investments held within the PIA. 
  • Up to €12,000 in annual contributions: Investors will be able to contribute up to €12,000 per year, with no minimum contribution announced. 
  • A range of investment options: Eligible investments are expected to include listed shares, bonds and qualifying investment funds, including ETFs. Certain complex and high-risk products will be excluded. 
  • Tax administration handled by the provider: The provider is expected to calculate, report and pay any tax due under the scheme. 

The final legislation will confirm the detailed rules and how the account will operate in practice. 

Who can open a PIA? 

Under the announced framework, the account is intended for individuals aged 18 or over who are resident in Ireland for tax purposes and have a Personal Public Service Number (PPSN). 

Further details on eligibility and account providers are expected as the scheme progresses towards launch. 

What does Budget 2027 mean for investors? 

The PIA is one of several investment-related changes announced in Budget 2027. 

The Government also announced a reduction in the tax rate applying to relevant Irish and equivalent offshore funds and Irish and foreign life assurance investment products, from 38% to 35%, effective from 1 January 2027. 

The PIA introduces a separate framework with its own contribution limit and tax structure. For investors, understanding how these changes compare with existing investment options will be important when deciding how to approach their financial goals. 

What could the PIA mean for you? An example 

Imagine you are 30 and decide to invest €200 per month through a Personal Investment Account (PIA) to help build wealth for the future. 

Your contributions could add up over time: 

  • After 5 years: €12,000 contributed 
  • After 10 years: €24,000 contributed 
  • After 20 years: €48,000 contributed 

These figures represent your contributions only and do not include investment growth, losses or fees. 

What if your investments grow? 

If your investments achieved an illustrative average annual return of 6%, compounded annually, your €200 monthly contributions could grow to approximately: 

  • After 5 years: €13,950 
  • After 10 years: €32,800 
  • After 20 years: €92,400 

These figures assume monthly contributions at the end of each month and a consistent 6% annual effective return. Actual investment returns fluctuate, and you could receive less than you invest.  

Disclaimer: These figures assume monthly contributions at the end of each month assuming a 6% annual return. Investment values can fall as well as rise. 

Is the PIA right for you? 

The new account could offer an additional option for people looking to invest for the longer term, but it will not automatically be the best choice for everyone. 

Before investing, consider your financial goals, existing savings, pension arrangements, investment timeframe and attitude to risk. You should also compare provider fees and investment options. 

Remember that the PIA is an investment account, not a guaranteed savings account. You could receive less than you originally invested, and the annual tax above the threshold may apply even when your investments have not generated a positive return. 

The most suitable approach will depend on your individual circumstances and wider financial plan. 

When will the PIA be available? 

The PIA is expected to launch on 1 July 2027, subject to legislation and providers making accounts available. 

In the meantime, you can start reviewing your financial goals, considering how much you could comfortably invest each month and keeping up to date with developments. 

Get ready for Ireland’s new Personal Investment Account 

At Alpha Wealth, we’re following the latest developments so you can understand what the scheme could mean for your financial future. 

Sign up for Alpha Wealth updates to stay informed about the PIA, including eligibility, tax treatment, investment options and what to consider before getting started. 

Nick Charalambous

Nick Charalambous

14th Oct 2026

Share this post

LinkedInTwitterFacebook

Related articles

Planning for Separation or Divorce: Key Financial Considerations
Advice

Planning for Separation or Divorce: Key Financial Considerations

Planning for Separation or Divorce: Key Financial Considerations 

As a financial adviser, and someone who has experienced separation and divorce personally, I understand that it can be one of the most difficult periods in a person’s life. 

Alongside the emotional and family considerations, separation or divorce also involves important financial decisions. From property and pensions to maintenance and tax, there is a lot to consider when moving from one household to two. 

Getting organised financially from the outset can help reduce some of the stress and uncertainty that comes with such a significant life change. 

Start by understanding your financial position 

The first step is to establish a clear picture of the finances of both parties. 

This includes: 

  • Income and regular expenditure 
  • Property and mortgages 
  • Savings and investments 
  • Pensions 
  • Loans and other debts 

This information is generally captured in an Affidavit of Means, which provides an overview of your financial circumstances. 

Having the full picture from the beginning can make discussions with your solicitor, financial adviser and, where appropriate, a mediator much more productive. 

How are assets divided? 

There is no simple formula for dividing assets following separation or divorce. Every family’s circumstances are different, and a number of factors may need to be considered, including: 

 
  • The length of the marriage 
  • Each person’s financial position 
  • Assets held before the marriage 
  • Each person’s income and earning capacity 
  • Existing debts and financial commitments 
  • The needs of any dependent children 

 What happens to the family home? 

The family home is often one of the biggest financial and emotional considerations. 

Depending on the circumstances, one person may remain in the property, one party may buy out the other’s interest, or the property may ultimately be sold. 

It is important not to look at the house in isolation. Someone may retain the family home but have limited savings, pension provision or disposable income. 

Looking at the overall financial position helps to understand what a proposed settlement could mean for both parties over the longer term. 

Don’t overlook pensions 

Pensions can be one of the most significant assets involved in a separation, particularly after a long marriage. However, they can easily be overlooked because they are less tangible than property or cash. 

A Pension Adjustment Order may be used to allocate pension benefits between spouses. This is an area where professional legal and financial advice is particularly important. 

What about maintenance and children? 

Where children are involved, their financial needs should remain central to discussions. 

There is no standard amount of child maintenance that applies to every family. The amount will depend on the individual circumstances, including the parents’ financial position, income and the needs of the children. 

It is also important to consider costs beyond monthly maintenance, such as: 

  • Childcare 
  • Education and school costs 
  • Medical expenses 
  • Extracurricular activities 

Spousal maintenance may also arise depending on the circumstances of the marriage and the financial position of each party. 

Don’t overlook tax 

Separation can change an individual’s tax position, including the tax credits available to them. 

For example, depending on the circumstances, a parent may qualify for the Single Person Child Carer Credit, which is worth €1,900 in 2026. 

There can also be different tax treatment for child and spousal maintenance. Certain transfers of assets between spouses or former spouses following separation or divorce may qualify for tax exemptions. 

It is therefore important to seek appropriate legal and tax advice before transferring property, investments or other significant assets. 

Reducing conflict and planning for the future 

Getting the right advice early can make a significant difference. 

A solicitor can advise on the legal aspects, while a financial adviser can help both parties understand the financial implications of different options. Mediation can also be helpful where both parties are willing to work towards an agreement. 

One of the best places to start is by getting organised. Gather your: 

  • Bank statements 
  • Mortgage details 
  • Pension statements 
  • Investment valuations 
  • Insurance policies 
  • Details of debts 
  • Household expenditure 

Finally, don’t just focus on getting through the separation. Moving from one household to two can significantly change the cost of living for both parties. 

Reviewing your budget, savings, pensions, insurance and longer-term financial goals can help you plan for what comes next. 

Knowledge gives you options. Understanding your financial position early can help you make informed decisions and plan for a more secure financial future beyond the separation. 

READ MORE 1st Oct 2026
Digitize or Die – Adopting Digitization in The Workplace
Advice

Digitize or Die – Adopting Digitization in The Workplace

”Survival of the fittest is not the strongest but the one that can adapt best” – Darwin
Now more than ever, adopting digitization in the workplace is essential for survival. Considering that the COVID-19 situation is evolving expeditiously it is increasingly unlikely that business practices will ever return to normal once the virus is contained. Social distancing has become the new norm and industries are set to change forever as new priorities have led to shifting demands from consumers.

In particular, the financial services industry where we were heavily reliant on face-to-face meetings.  The mantra ‘’innovate or die’’ has never been more pertinent and we had to adapt quickly and adopt a digital culture to remain competitive.

Innovating in the financial industry

Innovation is an essential element of Ireland’s overall economic development policy and is central to maintaining competitiveness in both global and domestic markets.  A study from Microsoft revealed that 80% of Irish SMEs are not as digitally shrewd as they seem to think and 48% are concerned about not keeping up with technological advancements. We believe it is crucial that SMEs overcome transformation anxiety and prioritise investing in digitalisation.

Similarly to most companies, we adopted the use of video calls for online consultations with clients. We had to familiarize ourselves with new software called DocuSign to manage electronic agreements which offers eSignature, a way to sign electronically on different devices. In the beginning, this was all very difficult but we can’t emphasise enough how overcoming transformation anxiety has helped us throughout this difficult period. We have made use of Webinars and offered free financial advice clinics to specific industries which have helped us build relationships, connect more deeply with our audience, and most importantly help those who are in need of financial advice.

Webinars

Webinars are extremely cost-effective compared to other marketing tools and hosting a webinar is a great way to generate content for your company’s online presence. Webinars are more about teaching than presentations. The biggest benefit of webinars belongs to the audience. That’s because the way content is explained in a webinar is really much, much more intimate than it could ever conceivably be in other kinds of presentations.

The pandemic has led to us exploring new avenues and webinars have certainly been a positive aspect of that. However, we are almost coming to the end of the webinar series with only two remaining. If you would like to attend our next webinar on Wednesday, July 8th you can register here. The series comes to an end on the 15th of July where we will be discussing how you can save 40% off your Tax. For more information please do not hesitate to contact us at (021) 206 1780 or contact@alphawealth.ie

Wednesday, July 8th – https://alphawealth.aidaform.com/financial-advice-webinar

Wednesday, July 15th – https://alphawealth.aidaform.com/tax-back-investment-options-registration-form

READ MORE 30th Jun 2020
Tracker Mortgage Scandal Q&A
Advice

Tracker Mortgage Scandal Q&A

Unless you have been hiding behind a rock for the past couple weeks, you would have noticed the coverage of the tracker mortgage scandal in the media. This is where banks have been accused of wrong doing to the public in relation to tracker mortgages taking out. I will run through a few questions that should help shed light on the area. The banks calculated that, even though they might lose money on these products, they could then “hook-in” the people who owned trackers and up-sell them more loans for cars, home improvements, and holidays, all of which would carry higher rates. The higher rates for other loans would off-set the losses on trackers and the banks got sneaky and reacted in the way they always do which is to screw the customer for the banker’s own mistakes and miscalculations.

Could you have been caught up in the tracker mortgage scandal?

Possibly. If you were ever on a tracker and were taken off it. No matter what the reason for this change, you could be one of 13,000 accounts to date affected, although that is by no means certain.

How would I know?

It is known that the banks are committed to going through their loan books to find all those who were affected. They were ordered by the Central Bank to make contact with those customers affected. Unfortunately, not everyone who was incorrectly denied a tracker has been contacted, and the banks and the Central Bank are still disagreeing over some accounts that the regulator considers were affected notwithstanding claims to the contrary by some banks.  And guess what there are many thousands more have been affected. Add a healthy figure onto the13, 000 or so that are currently in the system.et

So do I just have to wait until the Central Bank process is over?

Right now the Central Bank is “the only game in town”, keeping updated by reading the various media outlets will help assure you of what is happening.
Facts to date

  • €163m paid to customers in refunds and compensation a ‘fraction’ of money owed
  • Customers will ultimately foot bill for tracker scandal
  • Full extent of tracker scandal remains unclear

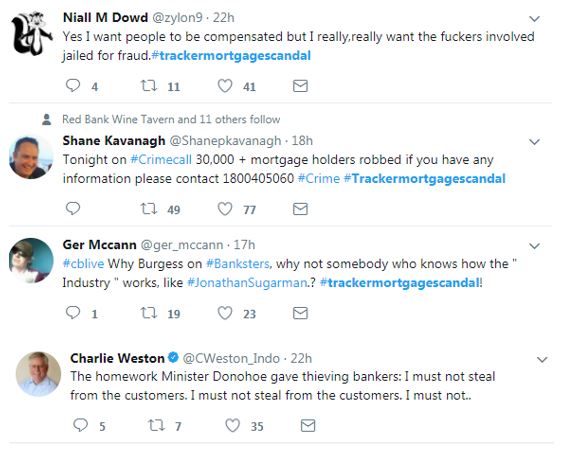
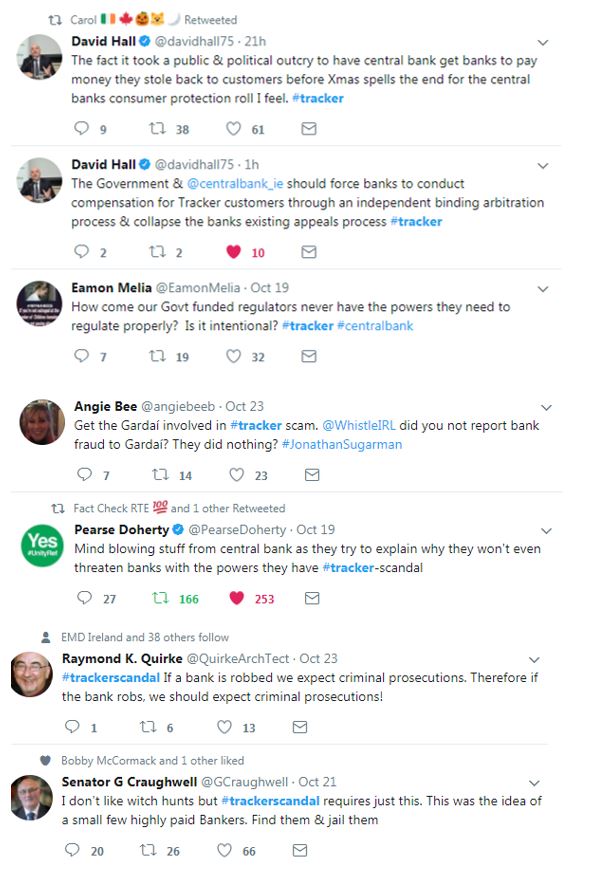
What has twitter got to say?

The big question ever has is should I take a legal action against my bank myself?

You could and by all means, you should do this. The legal avenue is open to anyone who considers they have been wronged. Unfortunately, this process is slow and very expensive. And many of those worst affected simply do not have the financial resources to take a High Court action, which is why the best advice is still to wait for the process to end.
 

When will it end?

It is progressing very slowly. This all started in 2015. Some banks have been proactive in dealing with cases; AIB and PTSB have dealt with a significant number of cases already. Ulster Bank have started to move. Bank of Ireland and KBC, on the other hand, have been very slow off the mark.

You will have some entitlements if you have been adversely affected by the bank’s misconduct.

  1. You will have to have the tracker restored.
  2. All the interest you overpaid will have to be repaid to you – or used pay off the mortgage.
  3. You will be entitled to compensation. (This will be decided by the bank initially and the Central Bank will review to see if this figure is suitable, the Central Bank is demanding the banks do more).

How do you fix it?

It seems that the whole issue is wrapped up by an industry who views success in the short-term, quarterly-results with which our global financial system has become obsessed.

The problem is the core culture that exists within these financial institutions. One has to ask themselves is it too much to demand a certain morality in the boardroom? Is it too much to ask for a few good men and women who apply morality to their business life? If not, we are in a troubling Ireland.

READ MORE 24th Oct 2017