Are You Earning More But Still Feel Like You Have No Money? 
Money

Are You Earning More But Still Feel Like You Have No Money? 

Nick Charalambous
Nick Charalambous6th Nov 2026 • 4 min read

Are You Earning More But Still Feel Like You Have No Money? 

You got the promotion, landed the new job or finally started earning the salary you’ve been working towards. So why does it still feel like there’s nothing left at the end of the month? 

The nicer coffees, weekend dinners, new clothes and little online shopping treats all start to add up. Before you know it, you’re earning more than ever but your bank balance doesn’t seem to reflect it. 

Sound familiar? You might be experiencing something called lifestyle creep. 

What is lifestyle creep? 

Lifestyle creep happens when your spending increases alongside your income. 

Think about it. When you first started working, you might have been happy making coffee at home, bringing lunch to work and keeping weekends relatively inexpensive. But as your salary increases, so do your expectations of what you can afford. 

Suddenly, eating out becomes a weekly habit, weekend trips become more frequent and the occasional treat turns into an everyday expense. 

There’s nothing wrong with enjoying the rewards of earning more, but when your spending increases at the same rate as your salary, you can end up no better off financially. 

Where does all the money go? 

Lifestyle creep rarely happens overnight. It’s usually a collection of small purchases that don’t seem like much at the time. 

A takeaway coffee here, another subscription there, a few extra nights out and perhaps a holiday you wouldn’t have considered a few years ago. 

Social media can also play a part. When everyone seems to be travelling, buying new cars and enjoying expensive weekends away, it’s easy to feel like you should be doing the same. 

The result? You end up spending more simply because you can, rather than because you necessarily want or need to. 

How can you avoid it? 

You don’t need to stop enjoying yourself or give up all the little luxuries. It’s about being a little more intentional with your money. 

Here are three simple ways to get started: 

  1. Give your pay rise a purpose.

When your salary increases, decide what to do with the extra money before it disappears into everyday spending. Consider putting some towards savings, investments or paying off debt. 

  1. Keep an eye on the little things.

Take a look at your subscriptions, takeaway spending and everyday purchases. You might be surprised by how quickly they add up. 

  1. Make saving a habit.

Set up an automatic transfer into your savings account each payday. That way, you’re putting money aside before you have the chance to spend it. 

  1. Think about your future self.

Make retirement saving part of your long-term financial plan. Regular contributions to your pension can help you build wealth over time. When a little extra money comes your way, whether it’s a Christmas bonus, pay rise or unexpected windfall, consider putting some of it towards your long-term financial goals rather than spending it all at once. 

It’s all about finding the balance. 

Earning more money should give you more opportunities, not just more expenses. 

There’s nothing wrong with treating yourself, booking that holiday or enjoying a nice dinner out. The important thing is making sure you’re also putting money towards your future. 

After all, financial freedom isn’t just about how much you earn. It’s about what you do with it. 

Nick Charalambous

Nick Charalambous

6th Nov 2026

Share this post

LinkedInTwitterFacebook

Related articles

How Vaping Can Save You Over €10,000?
Money

How Vaping Can Save You Over €10,000?

29% of smokers in Ireland currently use e-cigarettes as an aid to quitting smoking. If you’ve been a vaper for over 12 months then you’re classed as a non-smoker according to certain life insurance companies. This means you will pay the same price as a non-smoker.

However, applying to the wrong insurer will leave your pockets emptier. This brings about the argument around Smoking Vs Vaping:

You see some insurers aren’t as understanding when deciding how vaping affects life insurance. As soon as they hear you use e- cigarettes alarm bells will start ringing and they’ll class you as a smoker making you pay smoker rates. Is this fair what the insurers are doing? Well, smokers pay around twice as much as non-smokers because around 1 in 2 smokers will die of a smoking related disease. So, if I quit smoking using e-cigarettes, my chances of dying from a smoking related disease lessen and therefore I should get non-smoker rate?

The following conditions apply to the 6 main Life Insurers in Ireland:

  • Aviva Life & Pensions and New Ireland Assurance classify users as non-smokers, provided they have not smoked any other form of tobacco in the previous 12 months.
  • Friends First, Irish Life and Royal London classifies users as smokers.
  • Zurich Life applies a 50% loading to users who do not smoke any other form of tobacco and have not done so in the previous 12 months.

Is there really any difference in the price?

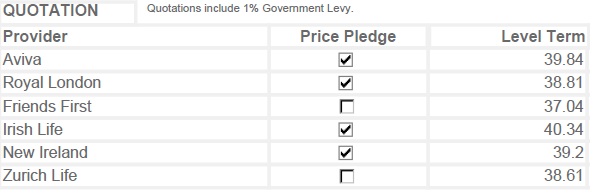
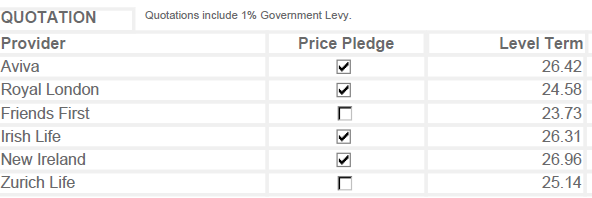
You better believe it, the difference in premium between a smoker and non-smoker when applying for life insurance is massive. To find out some exact figures I received a quote using this calculator which compares multiple insurance companies and distinguishes between smokers and non-smokers.

  • Name: Mark
  • Applicant: Smoker
  • Date of birth: 1/1/1990
  • Life Insurance: Cover of €500,000, over 20 years, paying yearly (price show below per month)

Name: Joe
Applicant: Non smoker
Date of birth: 1/1/1990
Life Insurance: Cover of €500,000, over 20 years, paying yearly (price show below per month)

These quotes show that a smoker will pay up to 92% more than a non-smoker.
To be classified as a non-smoker you will have to be off tobacco products for a minimum of 12 months. I’d try vaping now if I was you!

A heavier wallet

I speak about it time and time again in our blogs about making decisions that will lead to a more sustainable financial future. And guess what… vaping can save the average smoker €3,200 a year. That was only the cost of purchasing the materials. By taking into account your insurance premium you are looking at a saving around €3,400 a year on average.
If you weren’t convinced of the financial benefit of vaping, you should be now. If you have a Mortgage and given up smoking in the last 12+  months (even to go onto vaping) you will qualify for at least a 20% saving on your existing Mortgage Protection Plan through arranging a free consultation with us via phone email or face to face.

So the balls in your court…

Have you been vaping for the last 12 months and want non-smoker rates? Contact us today!
Reducing the cost is very easy.

READ MORE 12th Sept 2017
Want a Free Garmin Watch plus Money Back on Your Life Insurance Policy?
Money

Want a Free Garmin Watch plus Money Back on Your Life Insurance Policy?

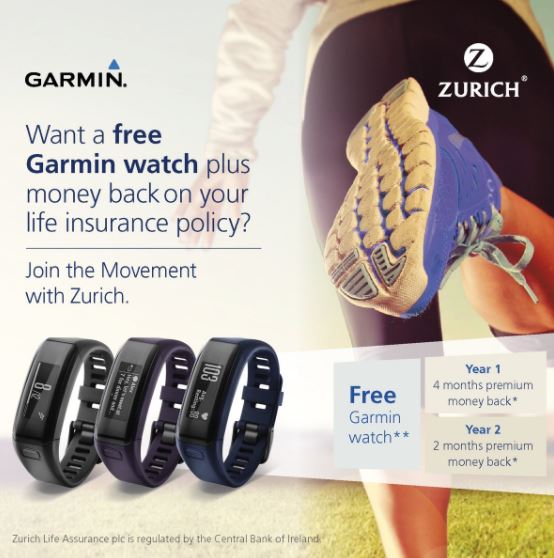
Alpha Wealth is now bringing this exciting Wearable Technology initiative to you in conjunction with Zurich Life.  When signing up for one of Zurich’s Term Protection or Serious Illness Policies you are rewarded with a Free Garmin Vivosmart wearable watch along with cash-back to the value of 6 month’s worth of premiums.  This is a pilot programme for 500 customers so they are whilst stocks last! 

To facilitate the pilot you will receive a Garmin Vivosmart HR watch (normally retails at €150) in exchange for granting Zurich and its reinsurance partner access to the data collected. As a thank you for your participation in the pilot, by sharing your data and maintaining a minimal level of activity (annual average of 2,000 steps per day), Zurich will also give you money back from your life insurance policy at the end of the first (4 months worth of premiums) and second year (2 months worth of premiums).

The purpose of this pilot is to see whether people will engage with wearable technology, whether it leads to fitness gains for our customers and whether it is something that could be used in insurance in Ireland in the future. Rest assured that this pilot programme is for research purposes only and will have no effect on your premiums or claims on current or future policies. The pilot study ends after 2 years but of course, your policy and the ability to use the watch will continue. At the end of the two-year period, all data with respect to the pilot will be anonymised so that you are no longer identifiable.

What can we expect in the future for wearable technology?

A whole new approach to life insurance that rewards policyholders for healthy living by offering:

  • Premium discounts for leading a healthy lifestyle
  • Valuable travel, shopping and entertainment-related rewards, and discounts from leading retailers
  • Industry-leading financial protection for customers
  • Opportunities to significantly save on the annual premiums

So be part of this new and innovative pilot scheme and join the Wearable Revolution!

READ MORE 2nd Aug 2017